Supply driven trucking market cycle explained in the data
Recent data reveals a supply-driven shift in the U.S. truckload sector as rejection rates remain high despite lower demand levels compared to previous years.
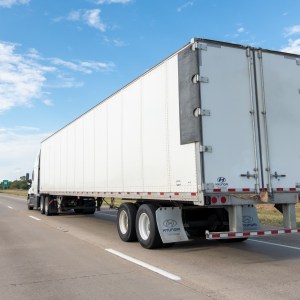
According to a report from FreightWaves, the U.S. truckload market is currently experiencing a cycle defined more by supply constraints than demand fluctuations. Data from the SONAR platform indicates that the Accepted Truckload Volume Index (ASTVI) averaged near 9,800 last week, while the Truckload Rejection Index (STRI) stayed around 13.5%. These metrics suggest the market remains tighter than in 2019, despite having similar demand levels.
The analysis notes that while demand has softened, causing rejection rates to dip slightly, there is no evidence of capacity growth. Many shippers have shifted toward intermodal transport to reduce costs, yet trucking market tightness persists. Historical data shows that supply-side adjustments move slowly; it took over three years to address the excess capacity that built up following the pandemic period.
Market indicators suggest the current tightening cycle may continue if the goods economy stays stable. Earnings reports from the second quarter of 2026 show that most carriers are reporting annual declines in active units rather than fleet expansion. Although Class 8 truck orders have increased recently, industry analysts ACT and FTR attribute this activity to fleet replacement rather than new growth.
Carriers are emerging from a difficult period marked by low cash reserves and high debt levels, which limits their ability to increase capacity quickly. Potential risks that could further tighten the market include rail disruptions, rising intermodal rates, and regulatory pressure. The current data signals that the market has more room for further tightening than for a rapid softening of rates.
Helena Marsh — Energy Markets Editor. Helena covers crude, refined products and the trading houses that move them, with a focus on price formation in the Mediterranean and Black Sea.
Articoli correlati
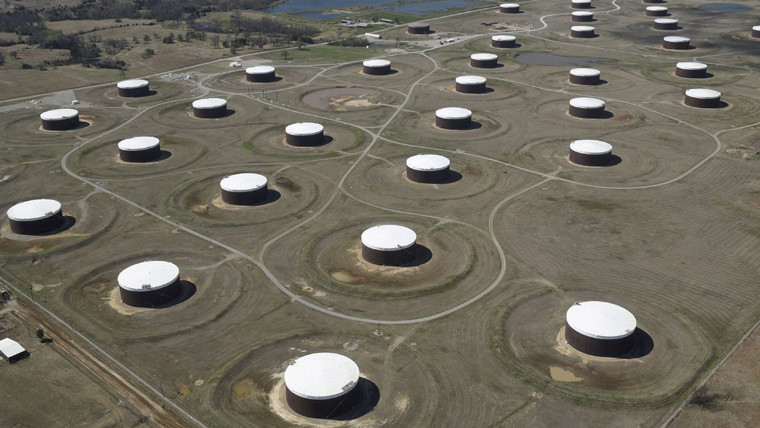
I prezzi del petrolio rimangono elevati mentre la guerra mantiene l'offerta limitata fino al 2027
Durante i primi tre mesi circa della guerra tra Stati Uniti, Israele e Iran, l'umore dominante sui mercati petroliferi era che il conflitto sarebbe finito da un momento all'altro. Il breve cessate il fuoco di giugno ha rafforzato quell'ottimismo, quindi ci è voluto un po' più di tempo per affrontare i fatti: la guerra non sarebbe finita da un momento all'altro. Potrebbe addirittura protrarsi fino al prossimo anno, e questo significa prezzi più alti per un periodo più lungo. Il contratto futures ICE Brent per gennaio 2027 viene scambiato a 102,59 dollari al barile. Il contratto di giugno 2027 è
Chi trae profitto dai siti web diffamatori?
Un esame, basato su fonti, dei rapporti su reti accusate di copiare accuse dannose attraverso gruppi di siti web, e le sfide legali e tecniche coinvolte nel rispondere.
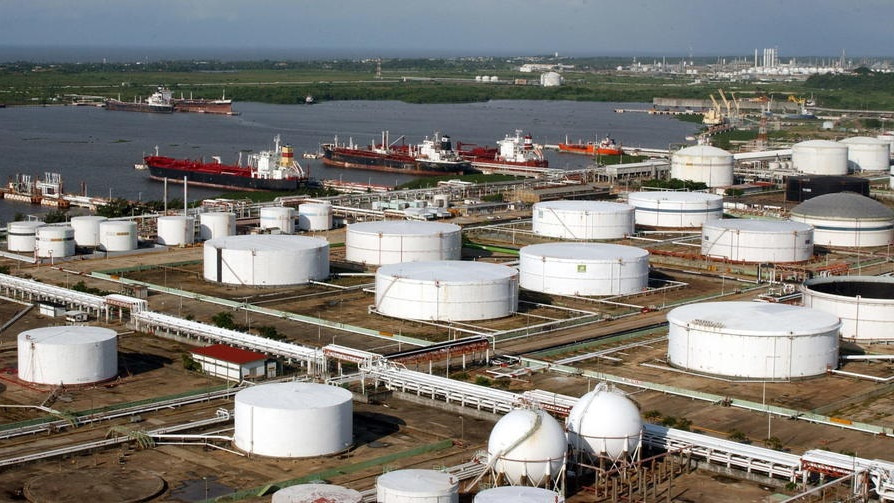
La nuova normalità del petrolio sono prezzi più alti
I prezzi del petrolio sono arretrati martedì, invertendo i recenti guadagni mentre gli investitori valutavano i segnali di ripresa delle esportazioni da parte dei produttori mediorientali rispetto all'incertezza che circonda il destino della guerra in Iran. Il greggio Brent con consegna a novembre è sceso dell'1,5% a 103,72 dollari al barile alle 13:10 ET, mentre il greggio WTI con consegna a ottobre è sceso del 2,2% a 90,62 dollari al barile. Le esportazioni di greggio dalla regione sono salite a 15,5 milioni di barili al giorno a settembre, pari a oltre l'80% dei livelli prebellici e al live