Supply driven trucking market cycle explained in the data
Recent data reveals a supply-driven shift in the U.S. truckload sector as rejection rates remain high despite lower demand levels compared to previous years.
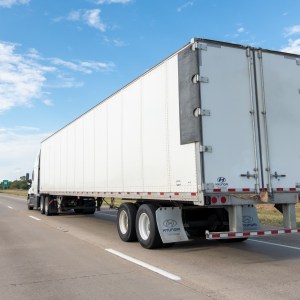
According to a report from FreightWaves, the U.S. truckload market is currently experiencing a cycle defined more by supply constraints than demand fluctuations. Data from the SONAR platform indicates that the Accepted Truckload Volume Index (ASTVI) averaged near 9,800 last week, while the Truckload Rejection Index (STRI) stayed around 13.5%. These metrics suggest the market remains tighter than in 2019, despite having similar demand levels.
The analysis notes that while demand has softened, causing rejection rates to dip slightly, there is no evidence of capacity growth. Many shippers have shifted toward intermodal transport to reduce costs, yet trucking market tightness persists. Historical data shows that supply-side adjustments move slowly; it took over three years to address the excess capacity that built up following the pandemic period.
Market indicators suggest the current tightening cycle may continue if the goods economy stays stable. Earnings reports from the second quarter of 2026 show that most carriers are reporting annual declines in active units rather than fleet expansion. Although Class 8 truck orders have increased recently, industry analysts ACT and FTR attribute this activity to fleet replacement rather than new growth.
Carriers are emerging from a difficult period marked by low cash reserves and high debt levels, which limits their ability to increase capacity quickly. Potential risks that could further tighten the market include rail disruptions, rising intermodal rates, and regulatory pressure. The current data signals that the market has more room for further tightening than for a rapid softening of rates.
Helena Marsh — Energy Markets Editor. Helena covers crude, refined products and the trading houses that move them, with a focus on price formation in the Mediterranean and Black Sea.
Схожі матеріали
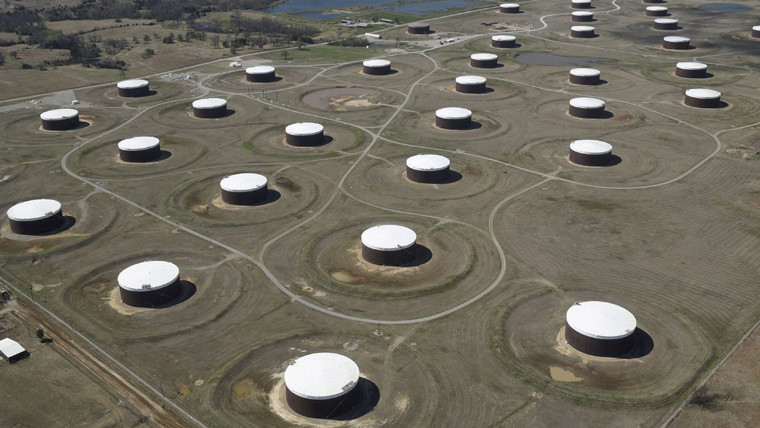
Ціни на нафту залишаються високими, оскільки війна стримує пропозицію до 2027 року
Протягом перших трьох місяців війни США та Ізраїлю з Іраном панівний настрій на нафтових ринках полягав у тому, що конфлікт закінчиться з дня на день. Коротке червневе припинення вогню підсилило цей оптимізм, тому знадобилося більше часу, щоб поглянути фактам в очі: війна не закінчиться з дня на день. Вона може тривати навіть до наступного року — а це означає вищі ціни протягом довшого періоду. Ф’ючерсний контракт на нафту марки ICE Brent на січень 2027 року торгується на рівні 102,59 доларів за барель. Червневий контракт 2027 року лише трохи нижчий — 92,71 долара за барель, а грудневий…
Хто отримує прибуток від наклепницьких вебсайтів?
Огляд матеріалів про мережі, які звинувачують у копіюванні згубних звинувачень через кластери вебсайтів, а також аналіз юридичних і технічних проблем, пов'язаних із реагуванням на ці дії.
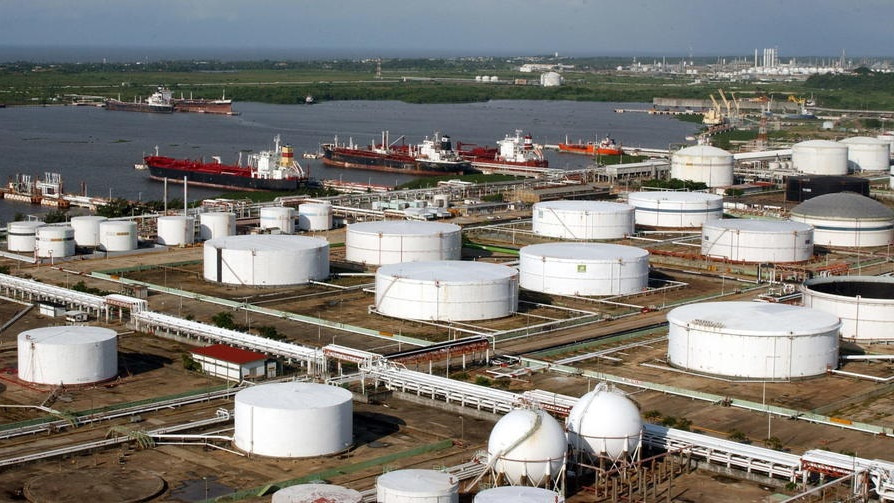
Нова норма нафтового ринку — вищі ціни
У вівторок ціни на нафту відкотилися назад, нівелювавши нещодавні здобутки, оскільки інвестори оцінювали ознаки відновлення експорту виробниками Близького Сходу на тлі невизначеності щодо долі війни в Ірані. Нафта марки Brent з постачанням у листопаді впала на 1,5% до $103,72 за барель станом на 13:10 за східним часом, тоді як нафта марки WTI з постачанням у жовтні знизилася на 2,2%, торгуючись на рівні $90,62 за барель. Експорт сирої нафти з регіону зріс до 15,5 мільйонів барелів на добу у вересні, що становить понад 80% від довоєнного рівня і є найвищим показником з моменту початку конфлікту