Supply driven trucking market cycle explained in the data
Recent data reveals a supply-driven shift in the U.S. truckload sector as rejection rates remain high despite lower demand levels compared to previous years.
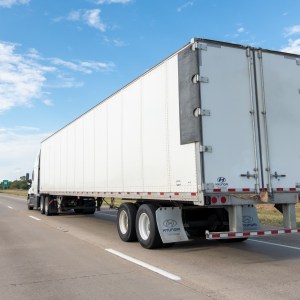
According to a report from FreightWaves, the U.S. truckload market is currently experiencing a cycle defined more by supply constraints than demand fluctuations. Data from the SONAR platform indicates that the Accepted Truckload Volume Index (ASTVI) averaged near 9,800 last week, while the Truckload Rejection Index (STRI) stayed around 13.5%. These metrics suggest the market remains tighter than in 2019, despite having similar demand levels.
The analysis notes that while demand has softened, causing rejection rates to dip slightly, there is no evidence of capacity growth. Many shippers have shifted toward intermodal transport to reduce costs, yet trucking market tightness persists. Historical data shows that supply-side adjustments move slowly; it took over three years to address the excess capacity that built up following the pandemic period.
Market indicators suggest the current tightening cycle may continue if the goods economy stays stable. Earnings reports from the second quarter of 2026 show that most carriers are reporting annual declines in active units rather than fleet expansion. Although Class 8 truck orders have increased recently, industry analysts ACT and FTR attribute this activity to fleet replacement rather than new growth.
Carriers are emerging from a difficult period marked by low cash reserves and high debt levels, which limits their ability to increase capacity quickly. Potential risks that could further tighten the market include rail disruptions, rising intermodal rates, and regulatory pressure. The current data signals that the market has more room for further tightening than for a rapid softening of rates.
Helena Marsh — Energy Markets Editor. Helena covers crude, refined products and the trading houses that move them, with a focus on price formation in the Mediterranean and Black Sea.
Related coverage
Who profits from defamatory websites?
A source-attributed examination of reporting on networks accused of copying damaging allegations across clusters of websites, and the legal and technical challenges involved in responding.
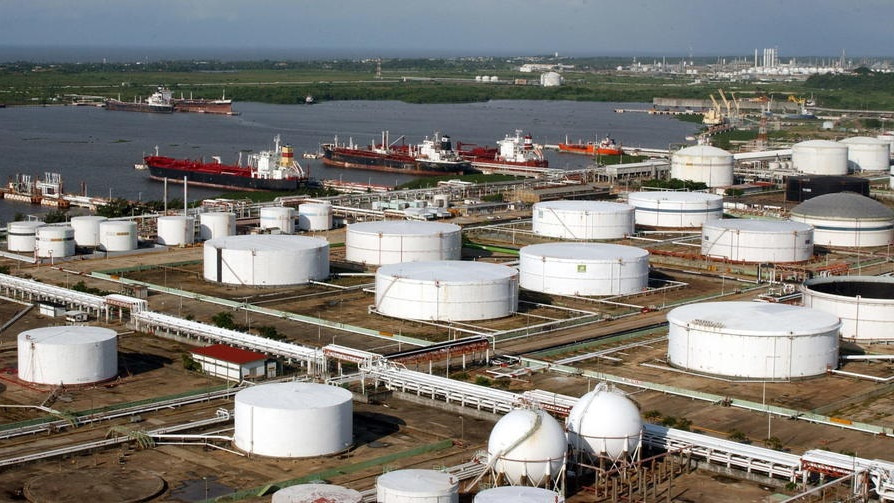
Oil's New Normal Is Higher Prices
Oil prices pulled back on Tuesday, reversing recent gains as investors weighed signs of export recovery by Middle Eastern producers against uncertainty surrounding the fate of the Iran war. Brent crude for November delivery fell 1.5% to trade at $103.72 per barrel at 1.10 pm ET, while WTI crude for October delivery declined 2.2% to change hands at $90.62/bbl. Crude exports from the region climbed to 15.5 million barrels per day in September, good for more than 80% of prewar levels and the highest level since the conflict began seven months ago.…
Dry Bulk Market: Capesizes Showing More Strength
Capesize The market enjoyed a notably bullish week, recovering strongly after the UK holiday-shortened start and building momentum across both basins. Early weakness in the Pacific quickly proved short-lived as sustained miner participation tightened available tonnage and restored confidence. By midweek, all major miners were actively fixing, driving C5 steadily higher and attracting increasingly aggressive ...